Category: Product

  • The Early-Exit Penalty: Why Leaving an Incentive Campaign Early Costs More Than You Think

    The Early-Exit Penalty: Why Leaving an Incentive Campaign Early Costs More Than You Think

    Most stakers assume an incentive campaign works like a savings account with a bonus rate: join, earn, leave whenever, keep everything you’ve accrued. That assumption is wrong often enough to matter. JPool’s incentive campaigns can attach a time-decay penalty to early departures — and because the mechanic is opt-in per campaign and easy to overlook, many participants only discover it the day they try to exit.

    This isn’t a penalty on your JSOL or your principal stake. It never touches the underlying stake pool exchange rate or your ability to redeem SOL. What’s at risk is narrower and easy to miss: unclaimed incentive rewards tied to a validator’s campaign, not the staking position itself.

    The Assumption Gap

    Searches for a “JSOL early unstaking penalty” usually conflate two separate systems. Redeeming JSOL back to SOL is governed by the stake pool program directly. Incentive campaign rewards are a completely separate layer sitting on top — created by individual validators, not by the pool itself. A campaign’s early-exit penalty only ever reshapes who receives reward tokens. It never touches stake, and a claim is never blocked outright — it’s only discounted.

    That distinction matters because it changes what you’re actually optimizing for when you exit early: not your position, but the reward you’ve already earned but haven’t collected.

    Two Separate Triggers, One Destination

    A campaign with a lockup enforces the penalty through two distinct actions, each scaled differently:

    • Pulling stake before the lock matures takes a slice of what you’ve earned so far, scaled by how much you withdrew and how early you did it. This is booked as a pending penalty and swept to the treasury on your next claim — or by anyone, permissionlessly, if you never claim at all.
    • Claiming before the lock matures applies a time-decayed cut directly to that claim: near the maximum penalty at the start of the lock, shrinking to zero as maturity approaches.

    In both cases, the destination is fixed: the penalty always routes to the protocol treasury, never to the validator running the campaign and never redistributed to other participants. This is the mechanism behind what shows up in searches as “Solana staking campaign exit fees” — it’s not a fee charged by JPool for the act of exiting, it’s a forfeiture of a portion of reward you hadn’t locked in yet.

    The Compounding Trap
    Editorial vector illustration of a geometric epoch ring holding a locked token within a cyclic timeframe.

    The lock doesn’t track a single timestamp — it tracks stake over time. That has a counterintuitive consequence: your first stake, any top-up, or rejoining after leaving all reset the lock to its full period from that exact moment. Staying put lets the clock run down. Adding more re-commits your entire position, not just the new portion.

    This is the part most participants miss. A participant who tops up their delegation two days before a campaign matures effectively restarts their full commitment window on their whole balance — including reward already earned under the old, nearly-matured clock.

    The Exit Math, Worked

    Concrete numbers make this tangible. Consider a fixed campaign with a 30-day lock and a 50% maximum penalty. A participant who has earned 100 reward tokens and claims on day 15 forfeits 25 tokens to the treasury and keeps 75. Claim on day 1 and the cut is near the full 50%. Hold to day 30 and the cut is zero — you keep everything.

    The same logic applies in reverse for proportional campaigns, where the early-exit cost isn’t a penalty but an opportunity cost baked into the reward-sharing curve: a participant staking from day 0 through a full 30-day proportional campaign can end up earning meaningfully more than a participant who joins on day 15, purely because early stake claims a larger share before dilution sets in.

    The Perpetual Campaign Blind Spot

    Here’s the mechanic almost no one checks before exiting: a lock can never extend past a campaign’s configured end date. If a campaign owner keeps rolling the end forward by only a short horizon each time, your effective lock is never longer than the time left until that end date — which can be far shorter than the advertised lock period. A participant reported right before an extension can carry almost no effective lock into the new period, even under a campaign advertising a 30-day term.

    Before assuming you’re “still locked,” check the campaign’s current end date against the lockup period — not just the lockup period alone.

    Why the Enforcement Boundary Matters

    The reason this system is trustworthy at all is that the boundary between earned and forfeited reward is enforced on-chain, not left to anyone’s discretion. Earned rewards up to the moment of any report stay yours indefinitely and can be claimed later — penalties only apply to the specific act of exiting or claiming early. This hard separation between what you’ve provably earned and what remains contingent is the same enforceability logic that distinguishes structural ownership claims from governance promises, explored in Governance Tokens Are Not Equity: Repricing Protocol Ownership.

    The Decision Framework

    Before triggering an early exit or an early claim on a locked incentive campaign, check three things:

    • How many days remain until the lock matures
    • Whether the campaign’s actual end date leaves the lock enough runway to bite
    • Whether you’re about to top up a position that would reset a nearly-matured clock

    The cost of leaving an incentive campaign early is never fixed — it decays with time, resets with every stake addition, and is measured against reward already earned, not against your underlying stake. Modeling that curve before you exit is the difference between a calculated decision and an expensive surprise.

  • Health Factor as a Warning System: How JPool’s Leveraged Staking Prevents Liquidation Before It Happens

    Health Factor as a Warning System: How JPool’s Leveraged Staking Prevents Liquidation Before It Happens

    Most discussions of Solana leveraged staking treat Health Factor as a single number to glance at occasionally. That framing misses what the metric actually is: a graduated early-warning system with distinct decision points, not a binary pass/fail gauge. This is a fundamentally different mechanism from validator-side bond health coverage — this piece is about what happens on your side of the ledger when you borrow against JSOL.

    The Three-Stage Warning System: Reading Health Factor as a Dashboard

    JPool’s Leveraged Staking derives Health Factor as your collateral value times the opening Loan-to-Value limit, divided by your debt. That construction gives the number a fixed anchor: it equals 1 exactly at the open-LTV limit — the most leverage you’re allowed to take on when you open — and falls below 1 as debt grows relative to collateral, bottoming out at the liquidation point. Each stage below corresponds to a different required response, not just a different color:

    Health Factor Status What it signals
    Above 1 Healthy Debt comfortably covered; you’re sitting above the open-LTV limit
    Danger threshold – 1 Warning You’ve crossed below the open-LTV limit and margin is compressing
    Below the danger threshold Danger Nearing the liquidation point, where the platform can sell collateral to cover the loan

    That danger threshold isn’t a round number you can memorize: the platform sets it dynamically, roughly halfway between 1 and the liquidation point, which itself depends on the pool’s open and liquidation LTVs. The critical detail most users miss: this scale is not evenly spaced in terms of risk. The distance from Healthy down to the danger threshold represents a wide buffer. The distance from there to liquidation can close in a fraction of that time, because it is being compressed by the same force that widened it — a persistent borrow rate above staking yield.

    What Actually Moves the Needle: Multiplier, Utilization, and the Liquidation Threshold

    Health Factor doesn’t move in isolation. It’s derived from your Loan-to-Value ratio and the lending platform’s parameters, and your LTV is set the moment you choose a leverage multiplier:

    Multiplier = 1 / (1 − LTV × (1 − Borrow Fee))

    A higher multiplier pulls more borrowed SOL into the position, which raises LTV and opens you closer to the HF=1 limit from the outset — before any market movement happens. This is why liquidation prevention starts at position opening, not during a crisis.

    Two additional metrics matter here that rarely get discussed:

    • Utilization Rate — the ratio of loan debt to collateral value. A rate of 60% means your debt equals 60% of your collateral’s value. This is effectively your LTV expressed as a live percentage, and it’s the number that actually triggers the shift between stages.
    • Liquidation Threshold — the specific collateral-value floor below which the lending platform is permitted to liquidate, independent of the Health Factor label itself.

    Your Borrow Limit — the initial ceiling set by your collateral and chosen LTV at position open — defines how much room exists before Utilization Rate approaches that threshold. Knowing your Borrow Limit at the outset is the difference between a planned deleverage and a forced one.

    The Compounding Trap: Why Erosion Isn’t Linear

    Minimalist flat vector artwork of a Health Factor gauge and a JSOL collateral token representing a leveraged staking position under pressure.

    Consider a position opened at 2.5× leverage: the borrowed SOL is staked, JSOL is minted as collateral, and a loan is taken against it. As long as staking yield on the amplified stake exceeds the borrow APR on the debt, Health Factor holds steady or improves — the collateral’s value compounds faster than the debt.

    The trap appears when that spread inverts. Debt accrues continuously; collateral only re-prices at the pace of staking rewards. If borrow APR overtakes staking yield for a sustained stretch, debt growth outpaces collateral growth, Utilization Rate climbs, and Health Factor moves through Warning toward Danger in accelerating steps — not a straight line. This is precisely why static one-time monitoring fails: the erosion rate itself increases as the position deteriorates.

    The Playbook: Matching Action to Alert Tier

    Effective liquidation prevention means pre-committing to an action at each stage, not deciding reactively:

    • Healthy → Warning: Confirm your Notification Trigger is set above the HF=1 limit, not at it. This is a configurable LTV level, and setting it early gives you a functioning warning system that fires before you cross the open-LTV line rather than after.
    • In Warning: This is the decision point for partial deleveraging — reducing exposure proportionally rather than waiting for a forced full exit.
    • In Danger: Add collateral or execute a partial close immediately. Waiting through this stage for the spread to self-correct is the single most common mistake in leveraged staking.
    • At the liquidation point: Liquidation authority has shifted to the lending platform. This is a boundary you plan around, never one you plan to manage from inside.

    Set your Reminder Interval short enough that a fast-moving Utilization Rate can’t cross two stages between alerts. A single notification cadence tuned for calm markets is a liquidation-prevention gap waiting to be found by volatile ones.

    Ownership Under Leverage: What You’re Really Pledging

    When JSOL sits idle in a wallet, ownership is straightforward. Once it’s deposited as collateral against a SOL loan, the question of what you actually control — versus what the lending platform can act on — becomes far more consequential. Understanding the difference between assumed rights and enforceable claims is the same discipline that separates leveraged stakers who monitor proactively from those who discover their real exposure only after a liquidation event.

    Health Factor is not a passive readout. It is the earliest signal in a chain of mechanical, rate-driven events — and treating each stage as a distinct decision point, backed by Utilization Rate and Liquidation Threshold awareness, is what actually prevents liquidation before it happens.

  • The Delegate-and-Forget Problem: Why Most Stakers Don’t Know What They’re Voting For

    The Delegate-and-Forget Problem: Why Most Stakers Don’t Know What They’re Voting For

    There is a governance decision embedded in every liquid staking deposit that almost no staker consciously makes. When you stake SOL into a liquid staking pool, you are not simply earning yield. You are delegating authority over which validators receive network weight — and by extension, which operators shape Solana’s consensus, which infrastructure philosophies get rewarded, and which behaviors get normalized across the validator set.

    Most stakers never think about this. That is the delegate-and-forget problem.


    The Invisible Ballot: What Staking Actually Decides

    Solana’s consensus mechanism is stake-weighted. Validators with more delegated SOL carry more influence over block production, vote confirmation, and ultimately, the network’s operational character. When a liquid staking protocol deploys pooled SOL across a validator set, it is casting votes — continuously, every epoch — on behalf of every depositor.

    This is not metaphorical. It is mechanical. The staker who deposits SOL and receives JSOL has transferred the delegation decision to the protocol’s automated engine. Whether that engine is thoughtful or indifferent, transparent or opaque, determines what kind of network those stakers are collectively building.

    DeFi governance voter apathy is typically discussed in the context of token-weighted voting on protocol upgrades — the kind of governance capture risk explored in detail in Governance Arbitrage: Protocol Forks as Hostile Takeovers. But in Solana liquid staking, the apathy problem runs deeper: it operates at the infrastructure layer, silently, every epoch, without a vote ever appearing on a governance dashboard.


    Why Low Participation Governance Risks Look Different on Solana
    Flat 2D vector illustration of a three-tiered geometric cascade structure channeling tokens across prioritized stepped platforms.

    In token-weighted governance systems, low participation risks are visible. Quorum failures are logged. Proposals that pass with 3% voter turnout are publicly auditable. The dysfunction is legible.

    In Solana validator delegation, the equivalent dysfunction is invisible by default. A staker who deposits into a protocol with no coherent delegation strategy — one that simply chases the highest APY validators regardless of stake concentration, infrastructure diversity, or operator accountability — has effectively cast a governance vote for network centralization. They did not intend to. They did not know they were doing it. But the on-chain outcome is identical to an intentional vote.

    This is the structural form of DeFi governance voter apathy that low participation governance risks frameworks rarely address: not the failure to vote, but the failure to recognize that you already have.

    The hidden cost is not just philosophical. Protocols that concentrate stake in a small number of high-APY validators amplify the superminority risk — the condition where a small group of validators controls enough stake to threaten consensus finality. Stakers who “delegate and forget” are not passive observers of this dynamic. They are its mechanism.


    The Accountability Gap: What Happens When Nobody Checks

    Even stakers who understand that their protocol makes delegation decisions on their behalf rarely know what criteria govern those decisions, how frequently those decisions are reviewed, or what happens when a validator deteriorates.

    This accountability gap is where the real cost of governance apathy accumulates. Consider the failure modes that go undetected when no one is watching:

    • A validator’s APY drops sharply mid-epoch — not because of network conditions, but because of operational neglect.
    • A validator’s infrastructure becomes concentrated in a single provider cluster, increasing correlated failure risk.
    • A validator’s stake grows beyond the threshold where it contributes to network health, tipping toward superminority territory.

    In a protocol with no systematic monitoring, these conditions persist until they cause visible harm. The staker has no signal. The protocol has no enforcement. The delegation decision made at deposit time remains in effect regardless of what happens afterward.

    This is the governance equivalent of a proxy vote that never expires and cannot be recalled — cast once, forgotten permanently.


    JPool’s Delegation Cascade: A Structured Answer to Apathy

    JPool’s Smart Delegation Strategy is designed to make the delegation decision continuous, criteria-driven, and accountable — rather than a one-time deposit choice that ages without review.

    The program operates through a cascading slot allocation system with three prioritized tiers:

    Priority Category Allocation
    1 Community Good (CG) 40% of slots
    2 Direct Stake (DS) 40% of slots + CG overflow
    3 Performance 20% minimum + DS overflow

    This cascade is not arbitrary. It encodes a specific governance philosophy: that network health requires more than APY optimization. Community Good validators — teams actively building open-source tools, DeFi protocols, developer infrastructure, and community resources for Solana — receive priority slot access. Their allocation is proportional to a scored impact assessment, not just their yield metrics.

    Within each tier, validators compete on documented, ranked criteria. Performance slots, for example, rank candidates first by 30-epoch average APY, then by credits ratio, then by shorter-window APY averages, then by validator age. This multi-factor ranking means that a validator cannot game a single metric to capture delegation. The criteria are published, the ranking is algorithmic, and the rebalancing is automatic.

    For stakers who don’t know what they’re voting for, this structure provides a concrete answer: when you stake with JPool, your delegation is governed by a published, tiered, algorithmically enforced framework — not by an opaque APY-maximization heuristic.


    The Suspicious Activity Gate: Enforcement at the Protocol Layer
    Minimalist flat 2D illustration of an oversized geometric filtration gate examining validator blocks on a continuous transit line.

    The most underappreciated element of JPool’s delegation accountability is not the scoring criteria — it is the continuous monitoring layer that governs what happens after a validator is admitted.

    JPool’s program flags validators as suspicious — with a visible warning in the Validator Dashboard — when specific conditions are detected:

    • Missing or unpublished validator metadata (name or avatar absent)
    • Poor cluster-wide performance, measured by average leader-leader vote latency falling below one standard deviation from the cluster average
    • A suspicious APY drop of more than 20% relative to the previous epoch, unless the validator’s bond health is at 100%

    This last condition is architecturally significant. A fully funded bond exempts a validator from the APY drop flag — because the bond itself is evidence of operational commitment. A validator who has posted and maintained their bond has demonstrated accountability in advance. The flag targets validators whose performance deteriorates without that structural commitment in place.

    The consequence of a suspicious flag is not immediate removal. It is a visible signal — to the operator, to delegators, and to the program’s monitoring layer — that investigation is warranted. This is governance enforcement at the protocol layer: not a vote, not a committee decision, but an automated accountability mechanism that operates every epoch regardless of whether any staker is paying attention.

    For stakers who have delegated and forgotten, this layer is doing the governance work they aren’t. That is the structural answer to the delegate-and-forget problem.


    What “Informed Delegation” Actually Requires

    The Solana validator delegation strategy question is not simply “which protocol has the best APY?” It is: “which protocol has a delegation framework I would endorse if I understood it fully?”

    That reframe changes the evaluation criteria entirely. An informed delegator asks:

    1. What are the explicit criteria for validator inclusion and removal?
    2. How frequently is the delegation decision reviewed and updated?
    3. What happens automatically when a validator deteriorates — and what is the evidence that this enforcement is real?
    4. Does the delegation philosophy reflect network health values beyond yield maximization?

    JPool’s program answers all four questions with documented, on-chain-enforced mechanisms: published eligibility requirements, every-epoch monitoring with 5-epoch full rebalancing cycles, graduated bond health responses, and a tiered allocation that explicitly rewards ecosystem contribution alongside performance.

    The delegate-and-forget problem is not solved by asking stakers to become validator analysts. It is solved by protocols that make the governance decision rigorous enough that delegation is worth trusting — and transparent enough that stakers can verify that trust rather than simply extending it.


    Explore JPool’s liquid staking infrastructure and validator delegation program at jpool.one.

  • The Collateral Premium Paradox: Why the Safest Assets Become the Most Dangerous

    The Collateral Premium Paradox: Why the Safest Assets Become the Most Dangerous

    There is a structural irony embedded in how DeFi collateral markets evolve. The assets that earn a reputation for safety attract the most borrowing demand. That demand drives deeper liquidity, which attracts more protocols to accept them. Over time, the “safe” asset becomes so deeply embedded in the collateral stack that its failure — however unlikely — is no longer a localized event. It becomes a systemic one.

    This is the collateral premium paradox: the very properties that make an asset desirable as collateral are the same properties that, at sufficient scale, transform it into a systemic risk vector.

    For Solana liquid staking tokens, this paradox is not theoretical. It is the central architectural question that separates genuinely secure liquid staking on Solana from assets that merely carry a safety narrative.


    When Safety Becomes Concentration
    Flat 2D illustration of a massive J coin and SOL coin balanced on a fulcrum, representing collateral risk.

    The collateral premium paradox operates through a predictable mechanism. An asset earns a safety premium — tighter spreads, higher LTV ratios, acceptance across more protocols — because it is perceived as low-risk. That premium creates a feedback loop: more protocols accept it, more users deposit it, and the asset’s share of total collateral across the ecosystem grows.

    The problem is not the asset’s individual risk profile. The problem is concentration. When a single asset class — or a single implementation of that asset class — represents a dominant share of collateral across multiple lending markets, the systemic impact of any failure in that asset’s underlying mechanics becomes disproportionate to its individual risk.

    This is a structural property of collateral markets, not a flaw in any specific protocol. It is why DeFi collateral risk cannot be evaluated at the asset level alone. The architecture of the asset — specifically, what happens when its underlying yield source underperforms, when its redemption path is stressed, or when its validator layer is compromised — determines whether its collateral role is structurally sound or structurally fragile.


    The Yield Layer Beneath the Collateral

    Liquid staking tokens are not static assets. They are yield-bearing instruments whose value is continuously updated by the performance of an underlying validator set. This creates a collateral risk dimension that does not exist for non-yield-bearing assets: the collateral’s value trajectory is a function of validator behavior.

    For most LSTs, this risk is opaque. Users and lending protocols accept the token as collateral based on its current exchange rate and its historical yield, without visibility into the mechanisms that govern what happens when the validator layer underperforms.

    JSOL’s architecture makes this layer explicit and structurally bounded. The JPool bond system requires every validator in the delegation program to post a unified bond — a minimum of 0.5 SOL per 1,000 SOL of total JPool stake — that covers both security risks and APY shortfalls relative to a benchmark rate. That benchmark, the Target APY, is calculated each epoch as the mean APY of the top 30 validators on Solana with non-JPool stake at or below 750,000 SOL, excluding superminority, blacklisted, and low-credit validators. It is recalculated every epoch.

    The critical architectural property here is not the bond requirement itself — it is what the bond enables: a pre-funded coverage mechanism for yield shortfalls. Shortfalls relative to the Target APY are covered from the validator’s bond, up to the posted bond amount. This means the yield layer beneath JSOL has a structural floor, not merely a policy commitment.


    Bond Health Gates: Collateral Integrity at the Validator Layer

    Visualizes the structural protection of validator bonds, matching the 'Bond Health Gates' section.
    Bond Health Consequence
    ≥ 100% Full delegation, no action required
    80–99% Grace period initiated; validator has time to top up
    50–79% Delegation cut by 50%
    < 50% Delegation capped to bond capacity; flagged for removal if bond is zero

    This architecture has a direct implication for collateral integrity. When a validator’s bond health degrades, the delegation program’s response is automatic and graduated — not discretionary. Stake is not left exposed to a deteriorating validator while governance deliberates. It is mechanically reduced and redistributed to healthy validators in the matching allocation, proportional to their direct stake.

    The security floor adds a further structural property: as long as a validator’s security bond is fully funded, performance exhaustion alone can only push bond health to the Warning threshold (80%). Delegation is not reduced until the security portion is actually impacted. This means the collateral’s yield source has a layered defense — security coverage is structurally senior to performance coverage.

    For DeFi protocols evaluating JSOL as collateral, this is not a marketing claim. It is an on-chain enforcement mechanism with documented, verifiable thresholds.


    The Solvency Guarantee: On-Chain Enforcement vs. Operational Promise

    The second structural layer relevant to collateral integrity is the incentive campaign architecture. JSOL’s incentive campaigns — which allow validators to run on-chain reward programs for delegators — are built around a hard solvency invariant: the vault must always hold at least the reserve.

    This invariant is enforced by three mechanisms operating simultaneously:

    • First, a fixed campaign reserves a participant’s entire future reward the moment their stake is reported, and refuses the update if the vault cannot cover it.
    • Second, every division in reward calculation rounds in the vault’s favor, so the campaign never promises a fraction more than it holds.
    • Third, after any payout, the campaign re-reads the vault and reverts the entire transaction if the balance has dropped below the reserve threshold.

    The consequence of this design is that a campaign failure mode surfaces as a rejected transaction — not as silently corrupted state or an underfunded promise that only becomes visible at claim time. This is the difference between a solvency guarantee enforced at the program layer and a solvency promise enforced by operational discipline.

    For collateral risk management, this distinction matters. An asset whose yield-generating mechanisms can fail silently — accumulating obligations that only surface under stress — is a categorically different collateral risk than one whose failure modes are designed to revert rather than propagate.


    The Structural Collateral Thesis

    The collateral premium paradox resolves differently depending on the architecture of the underlying asset. For assets whose safety is narrative-driven — dependent on the continued performance of an opaque validator set, the operational discipline of a custodial operator, or governance mechanisms that can be captured — the paradox is a genuine trap. Scale amplifies the systemic impact of failure without adding structural protection against it.

    For JSOL, the collateral premium paradox is bounded by architecture rather than narrative. These architectural bounds include:

    • The non-custodial on-chain program — built on the Solana Stake Pool Program, which has undergone 9 independent security audits by firms including Neodyme, Kudelski, Quantstamp, OtterSec, and Halborn — means that no private key held by JPool operators can move user funds.
    • The 2-of-3 multisig administrative floor means that no single operator can unilaterally alter pool parameters.
    • The bond health gate system means that validator deterioration triggers automatic, graduated responses rather than discretionary ones.

    These are not properties that can be voted away or altered by a single operator decision. They are structural properties of the system — the same kind of structural immunity discussed in the context of RPC-layer infrastructure design and access-path resilience, where design choices at the infrastructure layer determine whether a protocol survives adversarial conditions.

    The best Solana liquid staking architecture for risk management is not the one with the highest current APY or the deepest liquidity pool. It is the one whose safety properties are enforced on-chain, documented in audit reports, and bounded by mechanism rather than by trust.

    That is the structural answer to the collateral premium paradox.


    Explore JPool’s liquid staking infrastructure and validator delegation program at jpool.one.

  • Governance Arbitrage: Protocol Forks as Hostile Takeovers

    Governance Arbitrage: Protocol Forks as Hostile Takeovers

    DeFi governance is frequently described as a feature — decentralized communities steering protocol evolution. In practice, token-weighted voting has created an entirely new attack surface: one where capital accumulation, quorum manipulation, and fork credibility threats function as financial weapons. This is DeFi governance arbitrage, and it is one of the most underexplored structural risks in the ecosystem.


    The Governance Attack Surface: How Token Votes Become Weapons

    Token-weighted governance assumes that large token holders have aligned incentives with the protocol’s long-term health. This assumption breaks down the moment a token can be borrowed, flash-loaned, or accumulated cheaply through secondary market depression.

    The attack vector is straightforward: an adversarial actor accumulates or temporarily controls a sufficient token position to pass proposals that redirect treasury funds, alter fee parameters, or install malicious upgrade authorities. Because most governance systems require only a simple majority of participating votes — not total supply — the effective cost of control is often a fraction of the protocol’s TVL.

    This is governance arbitrage in its purest form: the attacker exploits the gap between the nominal cost of a governance attack (buying enough tokens to control the protocol permanently) and the effective cost (controlling enough votes to pass a single proposal during a low-participation window).

    The Beanstalk exploit of 2022 remains the canonical example: a flash loan was used to acquire a supermajority voting position within a single transaction, pass a malicious governance proposal, and drain the treasury — all atomically, before any community response was possible.


    The Quorum Trap: Why Low Participation Is a Feature for Attackers

    Most DeFi protocols set quorum thresholds between 4% and 10% of circulating supply. In practice, governance participation rarely exceeds these minimums. This creates a structural vulnerability: the attacker does not need to control a majority of the supply — only a majority of the votes cast.

    During periods of market stress, when token holders are distracted by price action or have migrated liquidity elsewhere, participation collapses further. An attacker who has quietly accumulated a small percentage of supply can achieve decisive governance control at exactly the moment the community is least vigilant.

    The quorum trap has a second dimension: proposal timing. Governance proposals typically have fixed voting windows of 48–72 hours. An attacker who submits a proposal during a holiday weekend, a major market event, or a period of community fragmentation can exploit the timing asymmetry — the attacker is prepared, the community is not.

    This is why governance arbitrage is structurally different from a smart contract exploit. A smart contract exploit requires finding a code vulnerability. Governance arbitrage requires only patience, capital efficiency, and timing.


    Protocol Forks as Hostile Takeover Credibility Threats
    Illustration of a balance scale tipped by a single coin, representing low quorum vulnerabilities in DeFi.

    Even when an outright governance attack is not executed, the credibility of a fork threat functions as leverage. A well-resourced actor who controls a meaningful token position can credibly threaten to fork the protocol — taking the codebase, the brand recognition, and a portion of the community — unless the existing governance structure accommodates their demands.

    This is the DeFi equivalent of a hostile takeover via proxy fight: the acquirer does not need to complete the acquisition to extract concessions. The threat itself reshapes governance outcomes.

    Protocol fork risks are amplified by three structural factors:

    • Open-source code is freely forkable. Any protocol with a public codebase can be forked with minimal technical cost. The fork’s credibility depends not on code originality but on the attacker’s ability to migrate liquidity and community attention.
    • Liquidity is the real moat, and it is portable. If an attacker can credibly promise better incentives on a forked protocol — funded by treasury assets extracted through governance — they can trigger liquidity migration that becomes self-fulfilling. As covered in our analysis of AMM liquidity migration dynamics and recursive TVL reflexivity, TVL is not sticky when incentive structures shift.
    • Token inflation as a governance weapon. A hostile governance proposal that passes a large token emission to the attacker’s address — framed as “ecosystem incentives” — can simultaneously dilute existing holders, fund the fork’s liquidity mining program, and demoralize the community. Protocols without sustainable revenue are particularly vulnerable to this vector because their token value depends entirely on narrative momentum.

    Why Algorithmic Delegation Cannot Be Forked

    The governance attack surface described above is a product of a specific design choice: concentrating protocol control in a token-weighted voting mechanism. JPool’s architecture makes a fundamentally different choice.

    Delegation decisions in JPool are executed algorithmically, not by token vote. The eligibility criteria — including the 750,000 SOL stake cap, the 10% commission ceiling, and the superminority exclusion — are encoded as operational parameters enforced by the program logic, not subject to a governance vote that can be captured by a temporary token majority.

    This is a structural immunity, not a policy preference. There is no governance proposal an attacker can pass to redirect JPool’s delegation strategy, because delegation execution does not run through a token-weighted voting mechanism. The attack surface simply does not exist in the same form.

    The bond system reinforces this immunity. Every validator in the JPool Delegation Program posts a unified bond — a minimum of 0.5 SOL per 1,000 SOL of total JPool stake — that covers both security risks and APY shortfalls. This bond requirement creates a skin-in-the-game filter that is orthogonal to token holdings: influence in the delegation program is earned through verifiable on-chain performance and posted collateral, not through token accumulation.


    The Multisig Floor: Administrative Governance Without a Single Point of Failure
    Flat 2D illustration of three interlocking keys protecting a Solana coin, representing multisig administrative governance.

    For the administrative actions that do require human authorization — adding or removing validators, updating pool parameters, adjusting fees — JPool uses a 2-of-3 multisig structure via Squads, with pool authority keys stored on offline hardware wallets.

    This design means that no single operator can unilaterally alter pool parameters. A governance attack that compromises one key holder cannot execute administrative changes. The 2-of-3 threshold is a hard floor: it eliminates the single point of failure that makes many DeFi governance systems vulnerable to targeted social engineering or key compromise.

    Critically, even a full compromise of the administrative multisig cannot redirect user funds. JPool’s non-custodial architecture means that SOL deposited into the pool is managed entirely by the on-chain Stake Pool Program — the same program that has undergone 9 independent security audits by leading firms including Neodyme, Kudelski, Quantstamp, OtterSec, and Halborn. No private key held by JPool operators can move user funds. The administrative attack surface is bounded by design.

    This stands in sharp contrast to protocols where a governance attack that captures the upgrade authority can redeploy an entirely new contract — one that does have custody of user funds.


    The Structural Contrast

    The DeFi governance arbitrage risk is not theoretical. It is a documented attack vector that has extracted hundreds of millions of dollars from protocols with token-weighted governance. The pattern is consistent: low quorum thresholds, portable liquidity, forkable code, and timing asymmetry combine to make governance capture cheaper than it appears.

    For infrastructure that underpins liquid staking — where user funds are continuously deployed — the governance attack surface is not an abstract concern. It is a due diligence question.

    JPool’s answer is architectural:

    • Algorithmic delegation execution
    • A non-custodial on-chain program with 9 independent audits
    • A 2-of-3 multisig administrative floor
    • A bond-based validator accountability system

    These are not governance policies that can be voted away. They are structural properties of the system.

    For a broader view of how infrastructure-layer vulnerabilities compound systemic DeFi risk, see our analysis of canonical bridge security models and RPC-layer centralization risks — two additional vectors where design choices at the infrastructure layer determine whether a protocol survives adversarial conditions.


    Explore JPool’s liquid staking infrastructure and validator delegation program at jpool.one.

  • MEV Supply Chain Centralization: Jito, Validators, and Order Flow

    MEV Supply Chain Centralization: Jito, Validators, and Order Flow

    Solana’s MEV landscape is not a free market. It is a supply chain — and like any supply chain, it has chokepoints. Understanding where those chokepoints sit, and how they interact with validator power distribution, is essential context for evaluating liquid staking safety on Solana in 2026.


    The MEV Supply Chain: A Two-Tier Validator Economy

    Maximal Extractable Value on Solana does not distribute evenly across the validator set. It concentrates — structurally, not accidentally.

    The mechanism is straightforward. Jito’s block engine introduced a separate transaction pipeline: searchers submit bundles of transactions to Jito’s relayer infrastructure, which routes them to validators running the Jito-Solana client. Validators who run this client gain access to a stream of MEV-optimized bundles that validators running the standard client do not see. The result is a bifurcated validator economy: operators with the infrastructure, technical capacity, and connectivity to run Jito-compatible nodes capture a materially larger share of per-epoch revenue than those who cannot or do not.

    This is not a criticism of Jito’s design. It is a description of what happens when a high-performance MEV infrastructure layer is introduced into a network where validator economics are already stratified by stake size. Larger validators with more resources adopt MEV infrastructure faster and more completely. Their revenue advantage compounds into higher APY, which attracts more stake, which increases their block production share, which increases their MEV capture. The feedback loop is self-reinforcing.

    For Solana’s decentralization, the implication is direct: MEV supply chain participation is not uniformly accessible, and the validators who benefit most from it are already the most staked. Order flow concentration and stake concentration reinforce each other.


    Order Flow on Solana: The Routing Layer Nobody Visualizes

    Visual representation of the bifurcated order flow routing layer.

    The phrase “order flow on Solana” is often used loosely. Precisely, it refers to the path that a transaction takes from origination — a user’s wallet, a DeFi protocol, a trading bot — to inclusion in a block. On a network without MEV infrastructure, this path is relatively flat: transactions enter the mempool and validators include them roughly in fee-priority order.

    Jito’s architecture changes this geometry. High-value transaction bundles — arbitrage sequences, liquidation captures, sandwich constructions — are routed through Jito’s relayer to validators running the Jito client. This means that the most economically valuable order flow on Solana does not reach all validators equally. It reaches the validators who are plugged into the MEV routing infrastructure.

    The consequence for network topology is significant. A validator that is not part of the MEV routing layer sees a systematically lower-value transaction stream. Over many epochs, this translates into lower APY relative to MEV-participating validators — not because of any failure in their node operation, but because of their position in the order flow supply chain.

    This dynamic creates a structural pressure on the validator set: operators who want to remain competitive on yield are incentivized to adopt MEV infrastructure, which further concentrates the order flow routing layer around a smaller set of technically sophisticated, well-resourced operators.


    The MEV Commission Gate: How JPool Enforces a Hard Ceiling

    One of the least-discussed aspects of how liquid staking protocols interact with MEV centralization is the commission enforcement layer. JPool’s delegation program requires that every validator in the program maintain a commission of 10% or less on both inflation rewards and MEV rewards. Exceeding this threshold on either dimension triggers instant removal from the program.

    This matters in the MEV context for a specific reason. As MEV revenue has grown as a share of total validator income, the commission rate on MEV rewards has become an increasingly material variable for delegator yield. A validator that charges a standard 5% inflation commission but takes a 20% MEV commission is effectively extracting a much larger share of total staking economics than the headline commission rate suggests.

    JPool’s unified commission cap — applied explicitly to MEV rewards, not just inflation — closes this extraction vector. Validators in the JPool delegation program cannot use MEV commission as a hidden margin lever. The 10% ceiling applies to the full revenue stack.

    This enforcement is not passive. JPool’s documentation specifies that commission exceeding 10% triggers instant removal from the delegation program — not a warning, not a grace period. The same instant removal applies to validators who:

    • Enter the superminority.
    • Are added to any blacklist (including the Jito Foundation’s).
    • Have non-JPool stake exceeding 750,000 SOL.

    The blacklist dimension is particularly relevant to MEV centralization: the Jito Foundation maintains its own blacklist of validators engaged in harmful MEV practices. JPool’s delegation criteria treat inclusion on this list as an automatic disqualification. The MEV supply chain’s own governance layer is thus directly integrated into JPool’s validator eligibility framework.


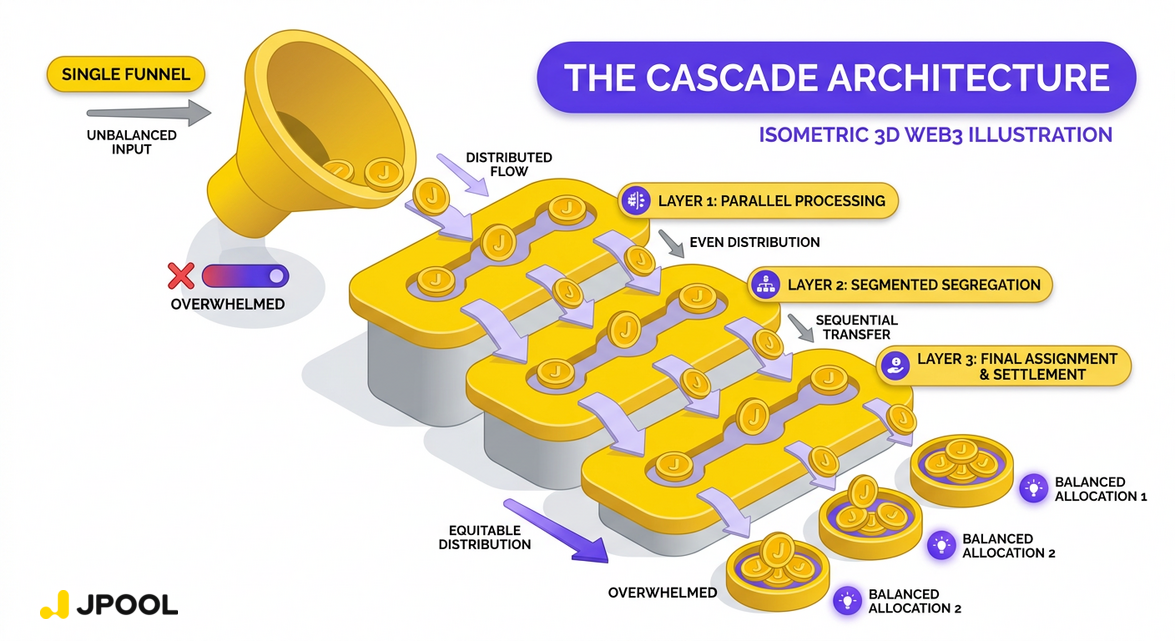
    The Cascade: How Slot Architecture Structurally Resists MEV-Driven Concentration

    Illustration of the Cascade architecture structurally resisting concentration.

    The deeper structural response to MEV centralization in JPool’s design is not the commission cap — it is the slot allocation architecture itself.

    JPool’s delegation program allocates validator slots through a cascading priority system with three tiers: Community Good validators (ecosystem builders), Direct Stake validators (operators who attract external delegators), and Performance validators (top APY operators). The allocation logic is explicitly designed to prevent any single performance dimension — including MEV-driven APY — from dominating the entire validator set.

    Consider what would happen without this architecture. A pure APY-maximizing delegation strategy would systematically funnel stake toward validators with the highest MEV capture — precisely the large, well-resourced operators already at the top of the MEV supply chain. The result would be a liquid staking pool that amplifies MEV-driven stake concentration rather than counteracting it.

    JPool’s Cascade prevents this outcome through structural design by prioritizing three tiers:

    • Community Good validators: Operators building open-source tools, DeFi infrastructure, and community resources receive priority allocation regardless of their MEV participation level.
    • Direct Stake validators: These receive matching proportional to the external stake they attract, not to their MEV yield.
    • Performance validators: These compete on a 30-epoch average APY metric that smooths out short-term MEV windfalls and rewards consistent, sustained operation.

    The result is a delegation framework where MEV-driven APY spikes do not automatically translate into larger pool allocations. A validator that captures an outsized MEV event in a single epoch does not leapfrog Community Good or Direct Stake validators in the priority queue. The Cascade’s architecture absorbs MEV volatility rather than amplifying it into stake concentration.

    JPool also scales its validator set linearly with TVL: one validator slot per 10,000 SOL. This means that as the pool grows, it distributes stake across a proportionally larger validator set rather than concentrating growth among existing participants. The decentralization benefit scales with adoption.


    The 5% Cap: The Hard Ceiling That MEV Cannot Override

    Even within the Performance tier — where APY is the primary ranking criterion — JPool enforces a hard constraint that MEV concentration cannot override: no single validator receives more than 5% of pool stake as pool delegation.

    This cap operates independently of how strong a validator’s MEV capture is. A validator that consistently ranks first in APY across every epoch cannot receive more than 5% of the pool’s total delegation. When a validator exceeds this cap, non-matching excess is redistributed to below-cap validators proportionally to their direct stake. DS Matching excess is held as an unallocated reserve to preserve proportionality.

    The practical effect is that JPool’s pool delegation cannot become a vehicle for MEV-driven stake concentration even if the broader Solana validator market moves in that direction. The 5% ceiling is a structural constraint, not a policy preference that can be overridden by market dynamics.

    This is the layer of liquid staking infrastructure that the MEV centralization discussion on Solana rarely reaches. The conversation typically focuses on whether MEV is good or bad for stakers, or on the yield uplift that MEV-participating validators provide. What it does not typically address is how the delegation architecture of a liquid staking pool either amplifies or counteracts the stake concentration dynamics that MEV infrastructure creates.

    As the Solana DeFi stack continues to converge, the structural properties of liquid staking delegation — how slots are allocated, how caps are enforced, how commission is monitored — become DeFi risk parameters, not just yield parameters. A liquid staking pool that delegates primarily to MEV-dominant validators is not simply optimizing yield. It is concentrating voting power and block production capacity in a way that has downstream implications for every protocol built on the network.

    JPool’s delegation architecture represents a systematic approach to ensuring that liquid staking stake does not become a passive accelerant for MEV-driven centralization on Solana. Key components include:

    • The Cascade allocation architecture
    • The 5% maximum stake cap
    • The MEV commission gate
    • Jito blacklist integration
    • A TVL-scaled validator set

    Explore JPool’s liquid staking infrastructure and validator delegation program at jpool.one.


    Subscribe to our digest pages and stay updated:
    Facebook Community · Instagram · Threads · Pinterest

  • Oracle Manipulation in Low-Latency Environments: What Solana’s Speed Creates — and How Resilient Liquid Staking Absorbs It

    Oracle Manipulation in Low-Latency Environments: What Solana’s Speed Creates — and How Resilient Liquid Staking Absorbs It

    Solana’s throughput is its defining competitive advantage. It is also, in specific DeFi contexts, a structural vulnerability surface that most liquid staking discussions have not yet addressed directly.

    The same sub-400-millisecond block times that make Solana attractive for high-frequency trading and real-time DeFi create a narrow but exploitable window: the gap between when a price moves on-chain and when an oracle feed updates to reflect it. In low-latency environments, that gap is not a rounding error. It is the attack surface.

    This article examines how oracle manipulation operates in Solana’s latency environment, why TWAP-based price feeds fail under targeted conditions, and what properties of liquid staking infrastructure — specifically JSOL’s architecture — create structural resistance to liquidation cascades triggered by oracle exploits.


    Why Solana’s Throughput Creates a Unique Oracle Attack Surface

    Traditional blockchain oracle manipulation is constrained by block times. On slower networks, the cost of holding a manipulated price for multiple blocks — paying gas across each one — makes sustained manipulation economically prohibitive for most targets.

    Solana’s architecture changes this calculus. With block times measured in milliseconds rather than seconds, a sophisticated actor can execute a sequence of transactions — a large spot trade to move price, a liquidation call against a position using the manipulated price, and a reversal trade — within a window so narrow that TWAP-based oracles cannot register the dislocation as a sustained price move.

    This is the core of the low-latency oracle manipulation problem: TWAP feeds are designed to smooth out noise over time, but on Solana, “over time” can be measured in hundreds of milliseconds. A price spike that lasts three blocks on Solana may be invisible to a TWAP window calibrated for slower networks — yet it can be sufficient to push a collateralized position past its liquidation threshold.

    The result is a class of exploit that does not require breaking any protocol. It requires only that the attacker understands the oracle’s update frequency better than the protocol’s liquidation engine does.


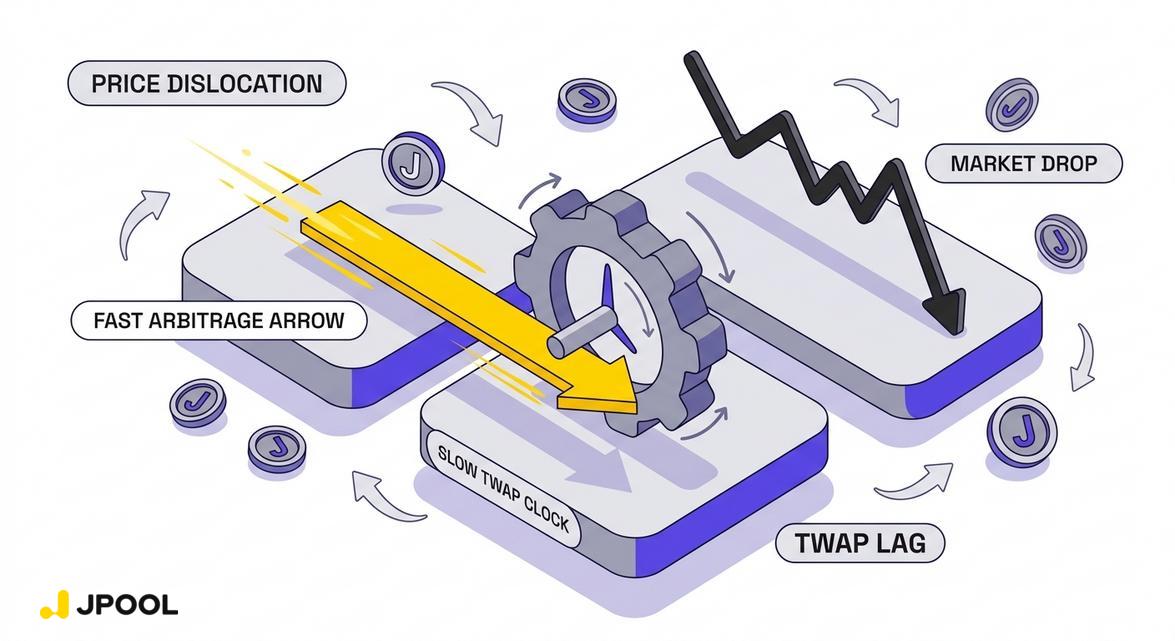
    The TWAP Failure Window: From Price Dislocation to Forced Liquidation

    Illustration of the TWAP failure window and price dislocation caused by low-latency manipulation.

    Time-Weighted Average Price feeds are the standard defense against spot price manipulation in DeFi. The logic is sound: averaging price over a window makes single-block manipulation prohibitively expensive. But TWAP’s effectiveness is a function of the ratio between the manipulation window and the TWAP window.

    On Solana, this ratio is compressed. Consider the sequence:

    • Price dislocation: An actor executes a large market sell on a thin liquidity pool, moving the spot price of an asset downward by a material percentage within a single block.
    • TWAP lag: Because the TWAP window has not yet incorporated sufficient post-dislocation blocks to average the price back toward fair value, the oracle feed reflects a price meaningfully below the true market price.
    • Liquidation trigger: A lending protocol using this oracle feed calculates that a collateralized position has crossed its Loan-to-Value threshold. The liquidation engine fires.
    • Reversal: The attacker reverses their initial trade, capturing the liquidation bonus and restoring the price — all within a window that may span only seconds.

    The critical vulnerability is not the TWAP mechanism itself. It is the assumption that the TWAP window is long enough relative to block time to absorb manipulation. On Solana, that assumption requires explicit calibration. Protocols that import TWAP parameters from slower-chain deployments without recalibrating for Solana’s block cadence are operating with a misconfigured defense.

    For users with collateralized DeFi positions — including those using liquid staking tokens as collateral — the consequence is asymmetric: the attacker profits from the liquidation bonus, the liquidated user loses collateral, and the oracle feed may return to fair value before any on-chain record of the manipulation is legible as such.


    Spot Price vs. Exchange Rate: Why JSOL’s Pricing Mechanism Is Structurally Different

    Illustration of JSOL's secure, epoch-anchored exchange rate providing stability compared to volatile spot prices.

    The oracle manipulation risk described above applies most acutely to assets whose collateral value is determined by spot price feeds. This is where JSOL’s pricing architecture diverges from the standard model in a way that has direct implications for low-latency DeFi risks.

    JSOL does not accrue value through a spot price that can be moved by a single large trade. Its value is determined by the JSOL↔SOL exchange rate — the ratio of total staked SOL plus accumulated rewards to total JSOL supply. As JPool’s documentation states: “Rewards are compounded by increasing the SOL-per-JSOL exchange rate over time. Your number of JSOL stays the same; each JSOL is simply redeemable for more SOL later.”

    This exchange rate is updated at the epoch boundary — approximately every two days — not by real-time market activity. It cannot be moved by a single block’s worth of trading volume. An actor who executes a large JSOL spot sale on a DEX moves the DEX pool price, but does not change the underlying exchange rate that determines JSOL’s fundamental redemption value.

    For lending protocols that price JSOL collateral against its exchange rate rather than its DEX spot price, this creates a meaningful structural defense: the collateral value of JSOL is epoch-anchored, not block-anchored. The manipulation window that enables low-latency oracle exploits against spot-priced assets does not apply in the same way to an asset whose fundamental value updates on a two-day cycle.

    This does not make JSOL immune to all oracle risk — DEX-based price feeds for JSOL can still diverge from the exchange rate during periods of thin liquidity. But it means that the specific attack vector of sub-second price dislocation triggering liquidation is structurally harder to execute against JSOL collateral than against assets with purely spot-based pricing.


    The Suspicious APY Drop Flag: An Underappreciated Early-Warning Layer

    Beyond the token’s pricing architecture, JPool’s validator monitoring system contains a mechanism that functions as an indirect defense against a related class of risk: sudden, unexplained performance anomalies that can signal validator-level compromise or manipulation.

    JPool’s documentation specifies that a validator is flagged as suspicious if it exhibits a suspicious APY drop of more than 20% relative to the previous epoch — unless the validator’s bond health is at 100%, in which case a fully funded bond exempts the validator from this check. A very suspicious APY drop — defined as an absolute change exceeding 50% — triggers instant removal from the delegation program.

    This mechanism matters in the oracle manipulation context for a specific reason: validators with degraded performance can affect the accuracy of on-chain yield data that downstream protocols may use to price staking derivatives. A validator that suddenly underperforms — whether due to technical failure, targeted attack, or deliberate commission manipulation — creates a discrepancy between the staking yield that JSOL’s exchange rate reflects and what a naive external observer might calculate from raw validator data.

    By flagging and removing anomalous validators before their performance degrades the pool’s aggregate yield, JPool’s monitoring layer reduces the surface area for yield-data manipulation that could affect how JSOL is priced or valued in external systems.

    It is also worth noting that JPool uses a 95% credits ratio threshold when calculating its Target APY benchmark — the reference yield that the bond system guarantees to stakers — filtering out validators with poor vote participation from that calculation. This ensures the benchmark itself is not distorted by validators with degraded block participation, which could otherwise cause the guaranteed yield floor to be set against an artificially low reference point.


    What Resilient Liquid Staking Infrastructure Actually Means for DeFi Collateral

    The oracle manipulation risk described in this article is not hypothetical. It is a known attack vector that has affected DeFi protocols on multiple chains, and Solana’s latency profile makes it a particularly relevant concern for any collateralized position.

    For users evaluating liquid staking tokens as DeFi collateral, the relevant question is not just “what yield does this token earn?” It is: “how is this token’s collateral value determined, and how resistant is that determination mechanism to low-latency manipulation?”

    JSOL’s epoch-anchored exchange rate, combined with JPool’s bond-backed yield floor and real-time validator anomaly detection, creates a collateral profile that is structurally more resistant to the specific oracle attack vectors that Solana’s speed enables. The bond system — where validators post collateral covering both security risks and APY shortfalls — means that JSOL’s exchange rate growth is not dependent on any single validator’s real-time performance. Even if individual validators are flagged, suspended, or removed, the pool’s aggregate yield trajectory remains protected by the bond mechanism.

    This is the layer of liquid staking infrastructure that most discussions of the Solana DeFi stack’s convergence do not surface explicitly: the structural properties of a liquid staking token’s pricing mechanism are a DeFi risk parameter, not just a yield parameter. In a low-latency environment where oracle manipulation is a live attack vector, the difference between a spot-priced asset and an epoch-anchored staking derivative is the difference between a liquidation target and a resilient collateral position.

    Liquid staking infrastructure that operates with audited non-custodial architecture, epoch-based exchange rate settlement, bond-backed yield guarantees, and real-time validator anomaly detection is not simply offering better staking yield. It is offering a fundamentally different risk profile for every DeFi position built on top of it.


    Explore JPool’s liquid staking infrastructure and start building a more resilient DeFi position at jpool.one.


    Subscribe to our digest pages and stay updated:
    Facebook Community · Instagram · Threads · Pinterest

  • The Next Phase of Liquid Staking: Restaking, Shared Security, and New Yield Layers

    The Next Phase of Liquid Staking: Restaking, Shared Security, and New Yield Layers

    Crypto staking has matured well beyond its original premise. In its earliest form, staking meant locking tokens to earn a single stream of network rewards — a straightforward trade of liquidity for yield. That model is no longer the ceiling. Today, liquid staking tokens have become programmable financial instruments, and the most sophisticated participants in Solana liquid staking are no longer asking “what is my staking APY?” — they are asking “how many yield layers can I stack on a single position?”

    This guide maps the architecture of that stack: what each layer is, how it works on Solana, and how JSOL is specifically designed to participate in each one.


    From Single-Stream to Multi-Layer: Why the Old Mental Model Is Obsolete

    The foundational assumption of early crypto staking was simple: stake → earn rewards → unstake. Liquidity was the sacrifice you made for yield. Liquid staking tokens broke that constraint — as covered in our guide to redemption liquidity, the ability to redeem or trade an LST at any time fundamentally changed the risk profile of staking.

    But the more consequential shift is less discussed: because JSOL is a standard Solana token, it can simultaneously serve as collateral, a liquidity pool asset, a leveraged staking instrument, and an ecosystem reward-earning unit — all while the underlying SOL remains staked and compounding. The yield is no longer a single number. It is a stack.

    Understanding that stack — and how to navigate it deliberately — is what separates passive stakers from strategic ones.


    Layer 1: The Base — Validator Performance Yield

    Every JSOL position begins here. When SOL is staked through JPool, the Smart Delegation Strategy allocates it across a curated set of validators evaluated on performance metrics including current APY, multi-epoch APY averages, stake concentration, and infrastructure diversity scores. The Validators.app score and Smart Validator Toolkit (SVT) adoption are also factored in.

    The result is that the SOL-per-JSOL exchange rate increases each epoch, automatically compounding staking rewards into the token’s value. No claiming, no manual action required.

    This base layer is the foundation everything else is built on — but it is only Layer 1. The complete mechanics of Solana staking yield, including MEV and priority fees, are covered in detail elsewhere. The strategic question here is: what do you do with JSOL once you hold it?


    Layer 2: DeFi Composability — Collateral and Liquidity Provision

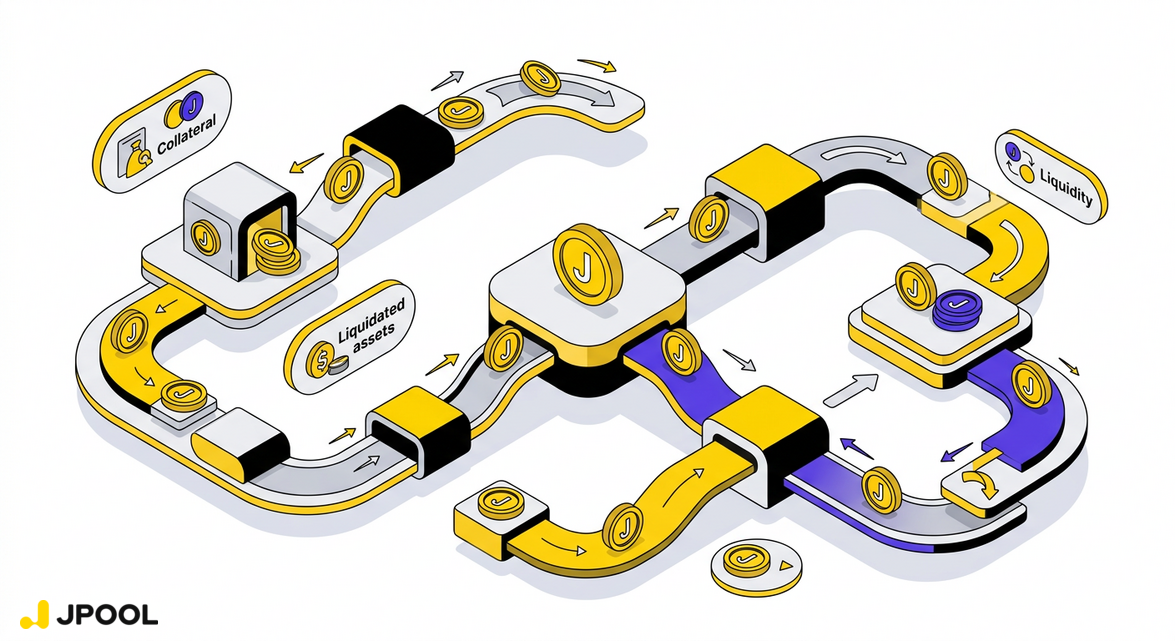
    Visualizing the concept of DeFi composability where a single asset is used in parallel streams.

    Because JSOL is a standard token, it can be deployed across Solana’s DeFi ecosystem while the underlying stake continues to accrue rewards. JPool’s documentation identifies two primary DeFi use cases:

    • Lending platform collateral: JSOL can be deposited to lending platforms as collateral to borrow against, generating additional yield or unlocking capital without exiting the staking position. The underlying SOL keeps compounding; the JSOL collateral earns the lending platform’s supply rate simultaneously.
    • Liquidity pool provision: JSOL can be provided as liquidity to liquidity pools, earning trading fees on top of base staking yield. This is a direct second income stream running in parallel to the staking rewards embedded in the token’s exchange rate.

    The key insight is simultaneity. Unlike traditional staking where deploying capital in DeFi means unstaking first, JSOL holders never have to choose between staking yield and DeFi yield — both run concurrently. This is the core value proposition of composability in Solana liquid staking, and it is what makes liquid staking tokens structurally different from locked native stake.

    The security architecture enabling this — specifically why JSOL can be trusted as collateral — is grounded in JPool’s use of the audited Solana Labs Stake Pool Program, detailed in our SPL vs. proprietary contracts analysis.


    Layer 3: Leveraged Staking — Amplifying the Base with Flash Loans

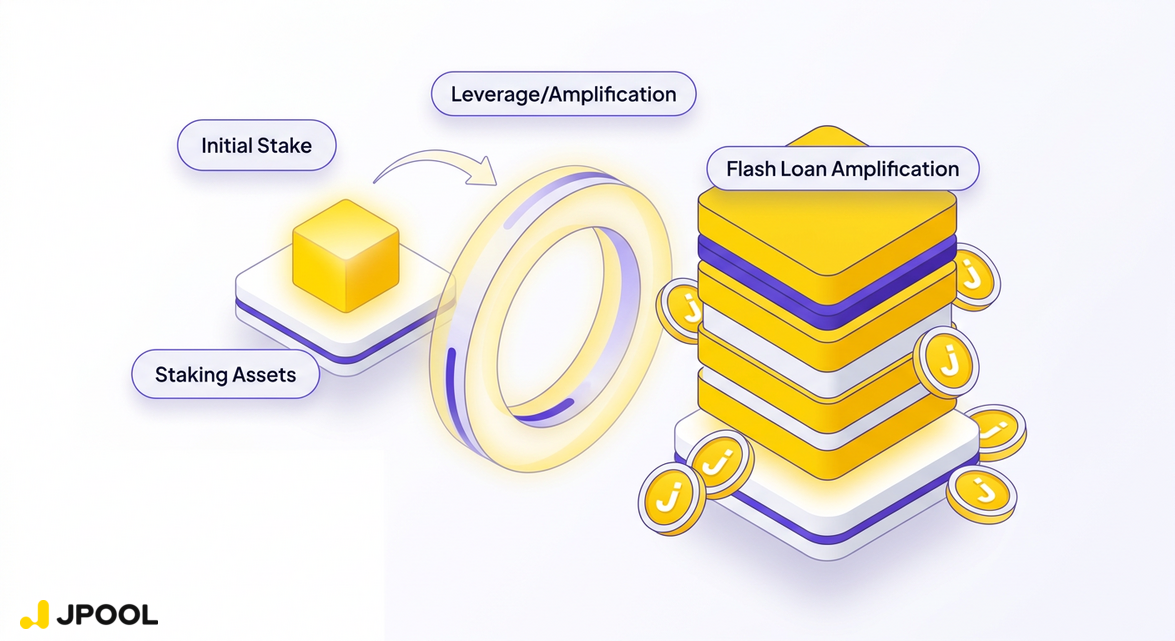
    Illustrating the mechanics of leveraged staking and flash loans amplifying a base position.

    JPool’s Leveraged Staking is the most mechanically sophisticated yield layer currently available on the platform, and it operates in a way that most users do not fully understand.

    Here is exactly how it works, step by step:

    1. Flash loan initiation: When a user selects a leverage multiplier, JPool takes out a flash loan to instantly provide the extra SOL needed for leverage. This is a temporary loan that must be repaid within the same transaction — it is never an open debt position at this stage.
    2. Combined staking: The user’s original SOL and the flash-loaned SOL are staked together to the chosen validator through JPool’s Direct Staking mechanism. The full combined amount earns staking rewards.
    3. JSOL minting and collateral deposit: JPool mints JSOL representing the full amplified stake and immediately deposits it as collateral on a lending platform (currently Save or Kamino).
    4. SOL borrow against collateral: Using the JSOL collateral, JPool borrows fresh SOL from the lending platform up to the allowed Loan-to-Value (LTV) ratio.
    5. Flash loan repayment: The user’s initial SOL and part of the borrowed SOL are used to repay the flash loan within the same transaction. The entire sequence is atomic — it either completes fully or reverts entirely.

    The result: the user holds a leveraged staking position with amplified JSOL collateral and an outstanding SOL loan. The yield differential — staking APY on the amplified stake minus the borrow APR on the loan — is the Leverage APY. For example, with a 2.5× leverage multiplier, a hypothetical staking APY, and a hypothetical borrow APR, a 100 SOL position effectively stakes 250 SOL, earning net yield on the spread between the two rates.

    The risk dimension is real and must be understood. The Health Factor (HF) and Loan-to-Value (LTV) indicators govern position safety. If borrow rates exceed staking APY for a sustained period, LTV rises and HF falls. If HF drops below 1.0, the lending platform can liquidate part of the JSOL collateral to cover the loan. JPool provides Telegram-based alerting for LTV thresholds to help users monitor this in real time. In practice, JPool notes that liquidation would require an extreme and prolonged scenario, but the risk is not zero.

    This layer is not appropriate for all users. It is a tool for those who have understood the base layer thoroughly and are prepared to actively monitor position health.


    Layer 4: Ecosystem Rewards — The JPool Holders Club

    The fourth yield layer operates entirely outside the on-chain staking and DeFi mechanics — and is frequently overlooked in yield calculations.

    The JPool Holders Club is a tiered membership program that rewards JSOL holders with JPoints, the ecosystem’s reward units. JPoints are earned through:

    • Simply holding JSOL — passive accumulation proportional to holdings
    • Using JSOL with JPool’s DeFi partners — rewarding the composability behavior described in Layer 2
    • Completing social tasks and referrals — ecosystem participation rewards

    Membership tier is represented by an NFT-based membership card issued by Albus Protocol, which tracks JPoint balance and tier status. As users advance through tiers, they unlock increasing reward levels. Boosters — multipliers that accelerate JPoints accumulation — can be earned through specific staking activities and DeFi partner engagement.

    The strategic implication: a user deploying JSOL in DeFi (Layer 2) is simultaneously earning Holders Club JPoints for that activity. The layers are not independent — they reinforce each other. Deploying JSOL as LP liquidity earns trading fees and JPoints. The ecosystem is designed so that deeper engagement compounds across multiple reward dimensions at once.


    The Yield Stack in Practice: A Decision Framework

    For users approaching Solana liquid staking strategically, the question is not which single layer to use — it is which combination of layers matches their risk tolerance and time commitment.

    Layer Mechanism Risk Level Active Monitoring Required?
    Layer 1: Base Staking Validator performance via Smart Delegation Low No
    Layer 2: DeFi Composability LP provision or lending collateral Low–Medium Minimal
    Layer 3: Leveraged Staking Flash loan amplification via Direct Staking Medium–High Yes (LTV/HF)
    Layer 4: Ecosystem Rewards JPoints via Holders Club Low No

    A conservative user maximizes Layers 1 and 4 with minimal effort. An intermediate user adds Layer 2 by deploying JSOL to a lending platform or LP, earning an additional yield stream without active management. An advanced user activates Layer 3, accepting the LTV monitoring requirement in exchange for amplified staking yield on the spread between staking APY and borrow APR.

    The architecture is designed so that each layer is opt-in and additive. No layer requires abandoning another. This is the structural advantage of liquid staking tokens over native locked stake: the position remains productive at every layer simultaneously.


    Shared Security and Restaking: The Emerging Frontier

    The concept of restaking — using already-staked assets to provide security guarantees to additional protocols — represents the next logical evolution of this yield stack. On other networks, restaking frameworks have demonstrated that validator stake can be committed to secure external services, creating additional yield streams for stakers who opt in.

    Solana’s architecture differs from other networks in meaningful ways, and restaking on Solana is still an emerging design space. The core principle, however, is directly relevant to liquid staking token holders: if a staked asset can be used to provide cryptoeconomic security to additional protocols beyond the base layer, the yield potential of that asset expands further.

    For JSOL holders, the composability foundation is already in place. JSOL’s status as a standard Solana token — tradable, usable as collateral, deployable in DeFi — means it is structurally positioned to participate in any restaking or shared security framework that emerges on Solana. The token does not need to be redesigned; the composability layer is already live.

    The decentralization implications of delegation concentration become especially relevant as restaking models mature: the health of the validator set underpinning any LST directly affects the security guarantees that LST can credibly offer to downstream protocols.


    Conclusion: Yield Is No Longer a Single Number

    The maturation of Solana liquid staking is not primarily a story about higher APY — it is a story about yield architecture. JSOL is not a passive savings instrument. It is a composable financial primitive that can simultaneously earn base staking rewards, DeFi yields, leveraged staking spreads, and ecosystem incentives — with each layer independently opt-in and additively stackable.

    The users who will capture the most value from the next phase of crypto staking are not those chasing the highest headline APY. They are those who understand the full stack, manage the risk dimensions of each layer deliberately, and position themselves in an LST infrastructure designed for composability from the ground up.

    Start staking SOL and building your yield stack with JSOL at JPool. https://jpool.one/

  • JPool Delegation Strategy, Powering Solana’s Liquidity and Growth

    JPool Delegation Strategy, Powering Solana’s Liquidity and Growth

    JPool Delegation Strategy

    Distributing Power, Driving Growth

    Why JPool Exists

    JPool prioritizes the long-term resilience and true decentralization of the Solana network by distributing more voting power to validators outside of the super-minority as well as directly incentivizing operators to attract more independent stake.

    While many protocols focus exclusively on maximizing APY by delegating to a limited number of nodes, we believe that true decentralization is impossible without independent
    builders and community leaders that are financially motivated to push the ecosystem forward. JPool not only supports mid range validators, but rewards them for launching new ecosystem projects and bringing more delegation to liquid staking market.

    Five Pillars

    • Fund the builders. Up to 40% of our pool allocation goes to Community Good validators – teams shipping open-source tools, DeFi protocols, developer infrastructure, and community resources that make the Solana ecosystem better for everyone.
    • Reward performers. Validators with consistently strong APY earn larger allocations through our Performance bucket. Performance is not all, but performance matters.
    • Grow liquid stake. JPool dedicates 45% of pool stake to direct delegations matching. Validators who attract external delegators and convert native stakers into liquid stakers will receive
      proportional matching. This is the single largest allocation in the pool.
    • Protect delegators. Every validator posts a JSOL bond that covers both possible security risks as well as APY shortfalls. Delegators shouldn’t pay for validators underperforming the bond system will guarantee the target APY.
    • Optimizing for Distribution. JPool maintains a strict 750K SOL stake limit per validator to keep the network balanced. Instead of over-funding a few dominant players, we distribute stake among high-performing, independent operators, ensuring a healthy and diverse validator set.

    Ecosystem growth engine

    These five pillars create a self-reinforcing cycle:

    More validators attract direct stake → more SOL flows into JSOL → deeper DeFi liquidity → JSOL becomes more useful → more stakers choose JPool → more TVL → more validator slots → broader decentralization → stronger network

    More validators attract direct stake → more SOL flows into JPool → more JSOL DeFi utility → more SOL flows into JPool

    We believe that JPool is more than simply a liquid staking pool – it has become an ecosystem growth engine that allows all players – delegators, validators, and builders, benefit from the others’ success.

    Scaling with Solana

    JPool grows its validator set linearly with TVL — 10 validators per 100K SOL. This keeps delegation meaningful (~10K SOL average per validator) while scaling decentralization as the pool grows. With the current TVL of 1.3M SOL, JPool will support 125 validators.

    No matter how large JPool gets, every validator will receive a meaningful portion of the stake.

    Who We Support

    Ecosystem Builders — validators who actively contribute to Solana’s growth by developing core infrastructure, launching innovative products, or expanding DeFi liquidity. We reward those who bring tangible value to the network – whether through technical tooling, community onboarding, or ecosystem support – with a dedicated stake allocation proportional to their impact.

    Growth-Oriented Operators – We prioritize validators who actively expand the ecosystem by attracting direct stake and facilitating the shift from native to liquid staking. JPool supports this growth by providing matching stake to those who successfully bring new liquidity and trust to the network.

    Reliable Infrastructure – Technical stability is essential for a healthy network. We allocate stake to validators who demonstrate consistent excellence through high uptime and low commission. By meeting the network’s performance benchmarks, these operators ensure that stakers receive steady, competitive rewards without compromising on decentralization.

    The Path to Growth

    Our tiers are dynamic, not static. We reward active contribution over historical status. Any validator can move into a higher-priority allocation by launching a project, increasing direct stake, or optimizing performance.

    Even if a validator doesn’t currently fit into the three main buckets, holding direct stake is enough to qualify for support. JPool provides additional “matching” stake on top of your existing direct delegations to amplify your growth and impact.

    Eligibility

    Every validator in JPool must meet baseline requirements:

    • Not on any blacklist (Solana Foundation, Jito Foundation, or internal)
    • Not in the superminority
    • Total stake under 750,000 SOL
    • Commission ≤ 10% on inflation and MEV rewards
    • Published name and avatar
    • No suspicious or poor performer flags
    • Active JSOL bond posted – minimum 1 SOL* (* soon will be replaced to JSOL)

    The Cascade: How Slots Are Allocated

    Slot Calculation: To maintain an optimal delegation balance, the total number of available slots in JPool is calculated by dividing our Total Value Locked (in SOL) by 10,000.
    We open one new validator slot for every 10,000 SOL in our Total Value Locked (TVL).

    Validator slots are allocated through a cascading priority system. Unused slots from higher-priority tiers flow down to the next:

    Priority Category Allocation, slots Who Qualifies
    1 Community Good (GS) 40% Validators with approved CG status
    2 Direct Stake (DS) 40% + CG overflow Validators with direct stake delegations
    3 Performance 20% minimum + DS overflow Top-30 APY validators (past 10-epoch average)
    • CG overflow: If there’s less CG validators than slots available, unused slots go to Direct Stake.
    • DS overflow: If there’s less DS validators than available slots, unused slots go toPerformance.
    • Performance floor: Performance always gets at least 20% of total slots — high-APY operators are never fully crowded out.

    Within each tier, validators compete on merit:

    • CG: Ranked by ecosystem impact score, then direct stake, then APY
    • DS: Ranked by direct stake size, then APY
    • Performance: Ranked by APY-30, then APY-10, then APY-3, then APY, then validator age

    How Stake Is Distributed

    Once validators earn their slots, pool stake is split into three buckets. Any unallocated remainder overflows into DS Matching, further rewarding validators who bring external stake.

    Bucket Share of Pool Stake Distribution
    Direct stake Matching 45% Proportional to direct stake
    Community Good 30% Proportional to CG impact score
    Performance 25% Proportional to performance weight

    DS Matching: Attract Stake, Get Matched

    The DS Matching bucket is the largest allocation in JPool — 45% of pool stake. Every SOL of direct stake you attract earns proportional matching from JPool.

    • In a DS slot: Full matching
    • Out of DS slot, with bond: Up to 50% matching
    • Out of DS slot, no bond: No matching

    Why this matters: JPool is the most powerful growth accelerator for Growth-Oriented Operators validators on Solana. Every delegator you attract is worth 1.5–2× more through matching — and we incentivize converting native stake to liquid stake, which deepens DeFi liquidity for the entire ecosystem.

    Community Good: Funding the Builders

    30% of pool stake flows to validators who are actively building for Solana, distributed proportionally by CG score.

    Area What We Look For
    Business model Non-commercial or free/freemium projects score highest
    Ecosystem impact Attracting developers, projects, liquidity, or users to Solana
    Open source Public code with permissive license (MIT, Apache, GPL)
    Reach Monthly active users, on-chain metrics, community size
    Visibility Media coverage, partnerships, ecosystem recognition

    CG scores (1–9) are assigned by the JPool review committee based on the validator’s ecosystem contribution. Higher score = proportionally more stake from the CG bucket. The committee evaluates:

    Criteria Points
    Basic point (monetisation)
    Non-commercial (no paid services) 3
    Free or freemium (≥50% free users) 2
    Commercial (fee / subscription) 0
    Bonus points (tracks)
    DEV +1
    PROJECTS +1
    LIQUIDITY +1
    USERS +1
    Open-source +1
    Free (MIT, Apache, GPL) +1
    1K+ MAU +1
    10K+ MAU +2
    Media coverage (Tier 1-2 level) +2

    Example: With 40 CG validators and a total score pool of 120, a validator with score 8 receives roughly 3× more CG stake than a validator with score 3.

    Performance: Rewarding Excellence

    25% of pool stake goes to validators in Performance slots, distributed by performance weight — a combination of APY strength.

    Global Cap

    No single validator receives more than 5% of pool stake as pool delegation. Excess is redistributed to validators with direct stake. This prevents concentration and ensures broad distribution.

    Examples

    Base on Epoch 935 data

    • JPool TVL = 1.5M SOL
    • Direct stake = 0.2M SOL

    Typical delegation outcomes at =1.3M SOL TVL with ~130 validators:

    Validator slot Delegation Bond Needed
    Performance slot (no direct stake; no community good; APY in top 30) 9,700 SOL 4.85 SOL
    Community good — score 4, 3,300 direct stake; APY (-0.1 lower from target APY) 19,700 SOL
    (9,400 SOL – Community Good;
    7,000 SOL – Direct stake matching;
    3,300 SOL – Direct stake)
    8.95 SOL
    Direct stake — 20,000; APY near target 63,000 SOL
    (43,000 SOL – Direct stake matching;
    20,000 SOL – Direct stake)
    31.5 SOL
    Out of slots – Direct stake 1,000 SOL APY near target 1,500 SOL
    (500 SOL – matching;
    1,000 SOL – Direct stake)
    1 SOL

    Every validator has a clear growth path: start with a Performance slot, then either build a project (→ CG) or attract delegators (→ DS) to multiply your allocation.

    Target APY & The Bond System

    How Target APY Works

    JPool calculates a Target APY – the benchmark yield guaranteed to stakers through the bond system.

    1. Take all Solana validators with total stake ≤ 750K SOL
    2. Exclude blacklisted, superminority, and low-quality validators
    3. Sort validators by past 10-epoch average APY
    4. Target APY = mean of the top 30 validators

    Recalculated every epoch (~2 days). The target reflects what the best mid-size validators on Solana are actually delivering.

    For delegators: You always earn the target APY. The bond covers any shortfall.

    For validators: Charging a commission does not disqualify you from receiving a delegation. You don’t need to match the target APY strictly through raw performance. If your actual yield falls short – whether due to your commission rate or slight technical variance – your bond simply covers the difference between the factual and target APY. This lets builders and community operators maintain their revenue models without being penalized.

    One Bond, Dual Purpose

    JPool simplifies collateral by using a single, unified bond that serves two critical functions: securing the network and guaranteeing delegation yields.

    1. Security (The Baseline)

    Purpose: Protects delegators against validator misbehavior, extended downtime, or exit risk.
    Requirement: 0.5 SOL per 1,000 SOL of your total validator JPool stake (both JPool delegation and direct delegations).
    Why total stake? By covering your full stake rather than just the pool’s allocation, this bond ensures stakers are fully protected against the total risk profile of your node.

    2. Performance (The Equalizer)

    Purpose: Covers any deficit between your factual (native) APY and the network target APY.
    Requirement: Dynamically calculated based on the size of the APY gap, your JPool delegation amount.
    The Advantage: If your native performance matches or exceeds the target APY, your performance bond requirement is strictly zero.

    Bond Health

    Your bond balance is split security-first: security bond is fully funded before any remainder goes to performance coverage.

    Health Level What Happens
    ≥ 100% Full delegation, no action needed
    80–99% Grace period starts — time to top up
    50–79% Stake cut 50%
    < 50% Suspension — delegation zeroed until replenished

    The security floor: As long as your security bond is fully funded, performance exhaustion alone can only push you down to 80% (Warning). Your delegation is safe from cuts until the security portion is actually impacted.


    Getting Into JPool

    New Validators

    • Meet baseline requirements – stake < 750K, commission ≤ 10%, published identity, no blacklist flags
    • Fund a bond – minimum 1 SOL
    • Compete for a slot – CG, DS, or Performance based on your strengths

    Community Good Applicants

    • Submit project details, metrics, and impact evidence via the CG application form
    • Review committee evaluates on a regular cycle
    • Score assigned based on the CG scoring criteria
    • Activated in the next rebalance cycle

    Direct Stake Validators

    Minimum 10 SOL direct stake to validator to qualify for a DS slot. Validators below 10 SOL still receive direct stake only and no matching. Ranking is purely by direct stake size.


    JSOL & DeFi

    JSOL is JPool’s liquid staking token – a first-class DeFi asset across Solana.

    For delegators: JSOL is listed on every major Solana DeFi platform: Jupiter, Raydium, Kamino, Orca, and many others. Your staked SOL stays liquid – use it as collateral, provide liquidity, or trade, all while earning staking yield.

    For validators: We’re building a DeFi incentive layer that rewards validators contributing to JSOL liquidity across protocols.

    For the ecosystem: More JPool TVL = more JSOL in circulation = deeper DeFi liquidity across Solana. Every SOL staked through JPool strengthens not just the validator network, but the entire DeFi ecosystem built on top of it.


    Operations

    Rebalancing

    Stake changes are gradual – no sudden large shifts:

    • Maximum 2.5% total pool change per epoch
    • Full rebalance every 2 epochs (migration period) then 5 epochs
    • Up to 10 new validators per epoch
    • Direct Stake delegation available instantly

    Hot Standby

    10 standby validators are always ready to fill any slot that opens from removal or suspension, ranked by 10-epoch APY and promoted automatically.

    Suspension & Recovery

    Bond health below 50% triggers suspension (delegation zeroed). Standard validators have 5 epochs to recover; DS-protected validators get 10 epochs. Failure to recover means permanent removal.

    Instant removal

    Instant removal triggers:

    • Commission > 10%
    • Total stake > 750K SOL
    • Blacklist
    • Superminority
    • Missing name/avatar

    Why Validators Choose JPool

    Benefit Details
    Meaningful delegation ~10,000 SOL average — significant enough to impact your economics
    DS Matching Largest matching program in Solana liquid staking — 45% of TVL
    Builder support 30% of stake reserved for Community Good projects
    Transparent Every parameter public, every decision has clear criteria
    No surprises Grace periods, warnings

    Why Delegators Choose JPool

    Benefit Details
    Guaranteed target APY Bond system covers any underperformance — you always earn the target
    Real decentralization 750K cap + broad distribution = genuine network security
    Ecosystem impact Your stake funds builders, community projects, and independent operators
    Full protection Security bond covers total validator stake — pool + direct
    Liquid & composable JSOL works across Solana DeFi – Jupiter, Raydium, Kamino, and more
    Always liquid Reserve fund ensures you can unstake when you need to

    Reserve Fund

    0.5% of TVL is reserved for unstake requests. Stakers can always withdraw.


    Resources
  • How Delegation Concentration Affects Solana’s Nakamoto Coefficient

    How Delegation Concentration Affects Solana’s Nakamoto Coefficient

    The Nakamoto Coefficient is the minimum number of independent validators that would need to collude to halt or corrupt a blockchain network. On Solana, where Proof-of-Stake means voting power is proportional to delegated stake, this number is directly shaped by how stake is distributed—not just across validators, but across the infrastructure they run on. When stake clusters, the Nakamoto Coefficient compresses. When it disperses, the network becomes structurally harder to attack or censor.

    Most conversations about Solana validator decentralization stop at the validator count. This analysis goes deeper into the specific scoring mechanics that determine whether liquid staking delegation actively improves or silently erodes the Nakamoto Coefficient over time.


    The Structural Problem: Why Stake Gravitates Toward Concentration

    Visualizing the structural problem of stake concentration where yield-chasing behavior leads to a superminority.

    Stake concentration is not the result of malicious intent—it is the predictable output of rational delegation behavior. Delegators optimizing purely for yield will naturally flow toward the highest-performing validators. High-performing validators, in turn, attract more stake, which can compound their influence over consensus. Left unchecked, this feedback loop produces a superminority: a small group of validators controlling enough stake to influence network outcomes.

    JPool’s inclusion criteria explicitly exclude any validator that is a member of the Superminority group. This is a hard gate, not a soft preference; a validator cannot participate in JPool’s delegation program at all if it already holds disproportionate consensus power. JPool also enforces a maximum stake cap of 750,000 SOL per validator, ensuring that even high-performing nodes cannot accumulate stake beyond a threshold that would dangerously concentrate voting weight.

    These are structural constraints. However, the more revealing mechanism is what happens inside the scoring system—where decentralization pressure is embedded directly into yield-weighted delegation.


    How Concentration Scores Function as a Decentralization Forcing Function

    JPool’s validator scoring system evaluates each validator across nine metrics, producing a total adjusted score between 3 and 39. Four of those nine metrics are dedicated exclusively to infrastructure diversity, measuring stake concentration across independent dimensions of the validator’s hosting environment.

    Each of these four concentration metrics is scored on a scale of 1 to 10, with a weight of 0.25 each. Critically, the scoring is relative: all possible concentration values across all validators are aggregated into 10 equal bands, and each validator is placed within that distribution. This means the score is not a static threshold; it is a continuously recalibrated ranking that responds to the actual state of stake distribution across the network at any given moment.

    The practical implication is significant. A validator hosted in an environment where cumulative stake has grown—even if that validator’s own stake has not changed—will receive a lower concentration score. The scoring system treats ecosystem-level concentration as the relevant variable, not just the individual node’s footprint. As JPool’s documentation states: “The more stake a group of validators in a single [hosting environment] attracts from delegators, the higher the concentration of stake… High rates of stake concentration are bad for Solana’s health because they bring down the network’s decentralization, which can create a point of failure.”

    This is a fundamentally different design philosophy from yield-only delegation. It means that two validators with identical APY performance can receive meaningfully different delegation weights based solely on where their infrastructure sits in the broader stake distribution.


    The Scoring Weight Asymmetry: What the Numbers Reveal

    Examining the full scoring table reveals a deliberate architectural choice. The four infrastructure diversity metrics together contribute a maximum of 10 adjusted-weight points (4 × 0.25 × 10). The three APY metrics together contribute a maximum of approximately 9.9 adjusted-weight points (3 × 0.33 × 10). In other words, infrastructure diversity and yield performance carry near-equal total weight in determining a validator’s score-based delegation.

    This parity is not accidental. It encodes a specific institutional stance: a validator’s contribution to network decentralization is as valuable as its contribution to staker yield. For delegators who assume liquid staking protocols simply chase the highest APY, this scoring architecture reveals a more complex reality.

    The Validators.app score (weight: 1, max: 11) and the Smart Validator Toolkit (SVT) bonus (weight: 4, max: 2 points) round out the system. SVT—JPool’s free validator management tool—rewards operators who adopt standardized, auditable node management practices:

    • A validator running SVT receives 2 points.
    • A validator running sv-manager receives 1 point.
    • Unmanaged nodes receive 0 points.

    This creates an incentive layer that correlates operational professionalism with delegation access, further filtering for validators that are less likely to become points of failure.


    Liquid Staking’s Dual Role: Amplifier or Corrective?

    Liquid staking protocols occupy a structurally powerful position in the Solana validator ecosystem. Because they aggregate retail delegation at scale, their internal allocation logic has outsized influence on where stake flows across the network. A protocol that delegates purely based on yield will amplify existing concentration. Conversely, a protocol that weights infrastructure diversity will act as a corrective force.

    JPool’s liquid staking delegation strategy is designed to function as the latter through several key mechanisms:

    • The Superminority exclusion removes already-concentrated validators from consideration entirely.
    • The 750,000 SOL cap prevents any single validator from accumulating excessive stake through the pool.
    • The concentration scoring system continuously redirects score-based delegation away from infrastructure environments where stake is already clustering—even as the pool grows.

    This architecture means that as JPool’s total staked SOL increases, the decentralization pressure it exerts on the network scales proportionally. More pooled SOL distributed through a concentration-aware scoring system means more stake actively flowing toward underrepresented infrastructure environments. The Nakamoto Coefficient, in this framing, is not just a network-level metric; it is a direct output of how delegation protocols are designed.

    For a deeper look at how validator selection and delegation mechanics interact with staking yield, see The Complete Guide to Solana Staking Yield Mechanics: MEV, Priority Fees, and Validator Revenue.


    The Compounding Effect: Community Good and the Ecosystem Multiplier

    Visualizing the compounding effect of community good and ecosystem growth through decentralized delegation.

    One dimension of JPool’s liquid staking delegation strategy that receives little attention in standard decentralization discussions is the Community Good framework. Validators whose earnings fund projects that introduce new functionality to the Solana ecosystem—across tracks including developer tooling, liquidity, and user acquisition—receive additional bonus stake.

    The Community Good score ranges from 1 to 14, and the resulting bonus stake is calculated by multiplying that score by 3,000 SOL. This means a maximum-scoring validator can receive up to 42,000 SOL in additional delegation. This is not a trivial amount for an independent validator. It creates a material economic incentive for smaller, ecosystem-contributing operators to remain viable—precisely the category of validator most at risk of being crowded out by stake concentration dynamics.

    The mechanism matters for the Nakamoto Coefficient because it actively subsidizes the long-tail of the validator set. Validators that contribute to ecosystem growth but may not yet command top-tier APY performance can remain economically sustainable through Community Good delegation. This expands the effective validator set that holds meaningful stake, which is the foundational requirement for a higher Nakamoto Coefficient.


    Conclusion: Delegation Design Is Network Design

    The Solana Nakamoto Coefficient is not a fixed property of the network; it is a dynamic output of how stake is allocated, epoch by epoch, across thousands of validators. Liquid staking protocols that manage significant pooled stake are, whether they acknowledge it or not, making active choices about network topology with every delegation cycle.

    JPool’s Smart Delegation Strategy encodes decentralization as a first-class objective—not through marketing language, but through concrete scoring mechanics. It implements this by:

    • Placing infrastructure diversity on equal footing with yield performance.
    • Hard-excluding Superminority validators.
    • Capping individual validator stake at 750,000 SOL.
    • Creating economic incentives for ecosystem-contributing operators to remain viable.

    Each of these mechanisms applies pressure against the concentration dynamics that compress the Nakamoto Coefficient.

    For delegators, the implication is clear: choosing a liquid staking delegation strategy is not just a yield decision. It is a vote on what kind of network Solana becomes.